Skip to content

RMDs & IRAs

RMD Penalty: 25%, Cut to 10% or $0 If You Act

Miss a required minimum distribution and the IRS excise tax is 25% of the amount you didn't take, cut to 10% if you fix it within the correction window, and often waived entirely if you take it out and explain. Enter the RMD and what you took to see the cost each way.

IRC §4974 after SECURE 2.0 Verified October 23, 2026

Your details

$
$

How you'll handle it

Results update as you type. We don’t save what you enter; shared links keep it after the “#”, which never reaches our servers.

Excise tax on the missed RMD

$1,200

10% of the $12,000 shortfall.

Not corrected

$3,000

25%

Corrected in time

$1,200

10%

With a granted waiver

$0

Fix it this month

1) Withdraw the missed amount now. 2) File Form 5329 for the year it was missed. 3) Write “RC” and the shortfall on line 54 and attach a short letter: what went wrong, that you’ve fixed it. 4) Don’t pay the tax up front — let the IRS decide.

Show the math

Since 2023 the excise tax is 25% of the amount not withdrawn, cut to 10% if you take it during the correction window (generally by the end of the second year after the miss, before the IRS assesses the tax). A waiver for reasonable error brings it to $0. You still owe regular income tax on the late withdrawal.

Next stepGet next year's RMD rightYour exact RMD with the uniform lifetime table.
Email these results

Missed RMD: The Four Steps to Fix It This Month

Fixing a missed RMD takes four steps, and the first is the one that matters most: get the money out now. The sooner you correct it, the stronger your case for a waiver and the lower the worst-case rate. (IRS: RMD FAQs)

  1. Withdraw the shortfall — the missed amount, from the account it should have come from.
  2. File Form 5329 for the year of the miss, even if you otherwise wouldn't file it.
  3. Request the waiver — write "RC" and the amount on the form and attach a short letter.
  4. Don't pay the excise tax up front. Let the IRS decide on the waiver first.

Do this, and most honest mistakes cost 10% at worst and nothing at best.
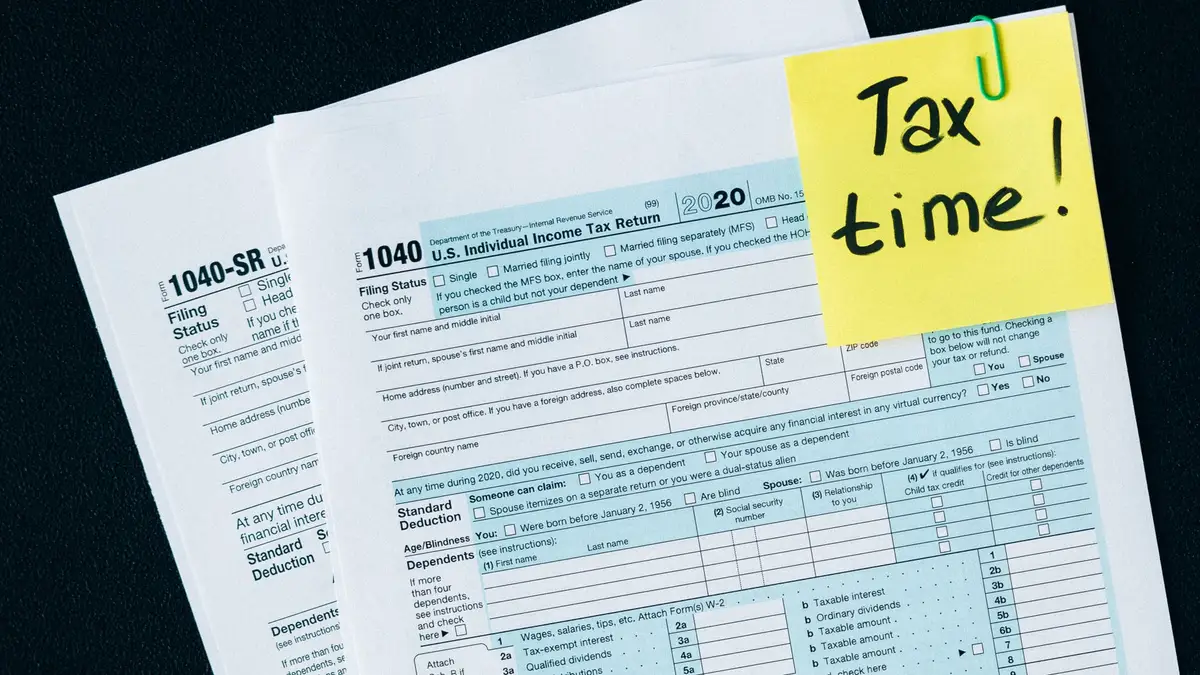
Tax forms on a desk with a sticky note
Photo: Nataliya Vaitkevich / Pexels

Missed RMD Penalty: Form 5329 and the Waiver Letter

The penalty is figured in Part IX of Form 5329: the required amount, the amount distributed, and the shortfall. To ask for a waiver, enter "RC" and the shortfall in parentheses next to the shortfall line, and explain in your letter. (IRS: About Form 5329)

A good letter is short and specific:

  • What happened (an illness, a custodian error, a misunderstanding of the new age)
  • When you discovered it and when you withdrew the shortfall
  • What you've done so it won't happen again

When does the correction window close?

The 10% rate applies if you take the missed amount before the IRS mails a deficiency notice or assesses the tax, and no later than the last day of the second tax year after the miss. After that, it's 25% (26 U.S.C. §4974).
Older woman looking stressed while going through paperwork
Photo: Nataliya Vaitkevich / Pexels

Our take: always ask for the waiver

Paying the excise tax without asking is the most expensive mistake here. The IRS commonly waives it for reasonable errors that are promptly corrected. Then set up the next one properly: get the amount from the RMD calculator, double-check your start year on the RMD age calculator, and keep the RMD table handy. Avoid a repeat: RMD deadline — December 31, and the April 1 exception.

Frequently asked questions

My missed RMD was from an inherited IRA. Is there relief?

For 2021 through 2024 the IRS waived penalties on certain missed annual RMDs under the 10-year rule. Annual RMDs from those inherited accounts are required from 2025, so a 2025 or later miss follows the normal rules.

Is the missed RMD still taxable income?

Yes. When you take it, the distribution is taxed as ordinary income in the year you actually withdraw it, in addition to any excise tax.

Can I roll the missed RMD into another account?

No. Required minimum distributions can never be rolled over. Withdraw it, then you can reinvest the money in a taxable account.

I have several IRAs. Did I miss if I took it from the wrong one?

No — for IRAs you can take the total from any of them. For 401(k)s, each plan's RMD must come from that plan.

Sources

Primary sources only. We re-check them whenever an agency publishes new figures.

  1. Congress
  2. IRS
  3. IRS

Did this answer your question?

Where people go next